Skip to content BEFORE AN ERP, CRM OR WMS CHANGE
Map it before you migrate it. Separate the workflow you need from the workarounds you inherited. Give the system team a reviewed view of the steps, data, rules and exceptions.
An old item code hides a unit-conversion decision Returned stock has no recorded disposition Credit authority lives in email instead of the record $1,500 fixed One workflow · Edge assessment
A Trail Map (your reviewed report), three priorities and a 90-day plan.
5 business days after your evidence is in. The call is a free 15-minute introduction. ProcessScout / Transform Real product · fictional data
Settle the workflow before the build
Current workflow Requirements Target system One focused workflow → a reviewed way forward The approach ↓ Explore the example ↓ Sample report ↗ Scope & price ↓ David Bell ProcessScout review lead
David brings 25 years of experience in operations and global finance, including Shell and Deutsche Bank. He was founder and CEO of JustPayroll through its 2024 acquisition.
David Bell leads the review approach. The analyst assigned to your assessment owns its recommendations and sign-off. Every paid Trail Map receives human review before delivery.
Meet David on LinkedIn ↗ HOW THE WORK MOVES FORWARD
Bring the process question before the build decision. Explore the method 01 Bring one workflow Confirm the question and scope. Bring authorized source records, a complete walkthrough, supporting documents and a process owner who can answer the open questions.
02 5 business days Five business days after your evidence checklist is complete. A named analyst reviews the evidence, assumptions, priorities and measurement design before the Trail Map is delivered.
03 A 90-day plan Receive three priorities, a baseline, next steps and one starter asset: a supported SOP, control checklist, requirements specification or automation blueprint. A blueprint describes the proposed change; implementation has its own scope.
EXPLORE A FICTIONAL ASSESSMENT
Follow the evidence.See the decisions. Redfern Industrial Supply is fictional. Its 50-return example traces item codes, disposition decisions and credit authority into a proposed ERP requirements brief.Tap a source or a workflow layer to inspect it.
Redfern Industrial Supply / Return-to-credit handoff ↗
THE WORK TODAY PROPOSED
Authorize → receive → search → rekey Identify → decide → link → review↗ Disposition and credit rules live in email Separate disposition from credit authority↗ Legacy returns screen, email, ERP Testable return-to-credit mapping↗ Old item and unit codes conflict Source item + unit + approved mapping↗ Unclear ownership of mapping exceptions Data owner, returns lead, controller↗ Approval is absent from the credit record Traceable evidence before draft acceptance↗ Tap a row ↗ ↗ Return and credit events ↗ Authored returns and draft-credit event register See which exceptions the new system must handle.
Cohort 50 closed return cases
Receipt-to-draft-ready duration 400 business hours across 50 returns; mean 8 hours
Item or unit code mismatch 12 of 50 returns Open the evidence ƒx Return-field mapping ↗ Authored return-field and decision workbook Inspect a mapping before it becomes a requirement.
Return RED-012 · legacy item AX-6 · unit CASE
Conversion question Confirm units per case before accepting target quantity
Required decisions Receipt, disposition and separate credit authority Open the evidence Returns-to-finance walkthrough ↗ Authored returns-clerk and finance walkthrough Keep the approval when the screen changes.
Start A returned case is received under a legacy item code
Handoff Returns clerk emails the disposition to finance
Gap Draft credit does not link the approval message Open the evidence ↗ People & decisions ↗ WHO DECIDES Data owner, returns lead, controller Returns process owner owns the proposed handoff.
Inspect the role design ↗ ↗ Approval checks ↗ REQUIRED EVIDENCE Traceable evidence before draft acceptance E01 · approval-link audit
Inspect the check ↗ 90 Sample report ↗ TRAIL MAP · REPORT EXAMPLE Redfern Industrial Supply Three priorities and a 90-day plan for return-to-credit handoff.
Read the fictional report ↗ Tap or click a source to explore. Fictional business · Proposed changes
See the finished client deliverable FOLLOW THE SOURCE EVIDENCE
Give requirements an evidence trail. ← →
01 / 03 Capture the decision between the screens. Follow a return from receipt to finance. The disposition and approval emails contain requirements the field list misses.
Inspect the evidence Redfern Industrial Supply / Workflow capture ↗
ProcessScout Recorder WORKFLOW Return-to-credit handoff Keep the approval when the screen changes.
00:12Authorize a return with an old item code Step captured
00:29Receive stock without a disposition Exception
00:46Find credit approval in an email Step captured
Synthetic recording sequence · No live capture on this page
02 / 03 Map the control before the target field. Show which records and decisions make a draft credit ready. Then use that boundary to write a testable requirement.
Inspect the evidence Redfern Industrial Supply / Workflow map ↗
01 Authorize a return with an old item code ↓ Map the item and unit explicitly
02 Receive stock without a disposition ↓ Record the authorized next action
03 Find credit approval in an email ↓ Link approval to the return record
04 Rekey the draft credit ↓ Test mapped values before approval
03 / 03 Give the implementation team a decision owner. The data owner settles units, the returns lead settles disposition, and the controller settles credit authority.
Inspect the evidence Redfern Industrial Supply / People & decisions ↗
ACCOUNTABLE Returns process owner
Data owner Validates item and unit mappings Returns lead Confirms receipt and disposition decisions Finance controller Defines the credit approval evidence Proposed responsibilities for Redfern Industrial Supply. Confirm authority and backup coverage before use.
Confirm scope and permission before capturing work. Avoid credentials, payment-card details and unnecessary personal data. Read the capture guide ↗
EVIDENCE Open the report SEE A FINISHED DELIVERABLE
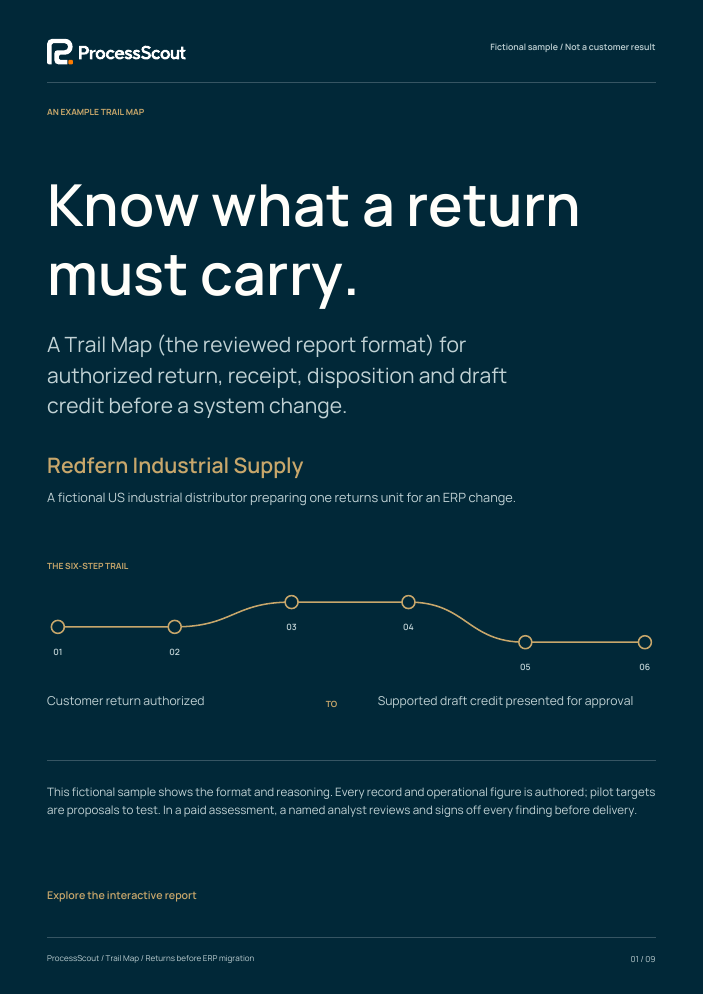
A return-to-credit brief you can inspect. Redfern’s fictional report shows twelve item or unit mismatches, seven missing dispositions and nine unlinked credit approvals. Each becomes a requirement with a decision owner and validation step.
Report + evidence 3 opportunities 90-day plan
A fictional sample built from authored evidence. It shows the format, not a customer result.
BEFORE YOU DECIDE
Our implementation partner is already mapping requirements. Use this assessment for one disputed or poorly documented workflow. The report gives your partner source-linked decisions, unresolved questions and a bounded requirements specification they can validate in the target system.
THE EDGE ASSESSMENT
One workflow. Fixed scope. $1,500USD / fixed assessment
The $1,500 USD assessment can include a supported requirements specification or automation blueprint as its starter asset. A blueprint is a design. Migration, integration, configuration and production deployment require separate scope and approval.
Three evidence-backed opportunities, or your fee back. If ProcessScout cannot identify at least three evidence-backed opportunities from a good-faith intake, the assessment fee is refunded under the assessment terms. This is a deliverable guarantee, not a promise of realized savings.
Read the guarantee and refund terms ↗ Five business days after your evidence checklist is complete.
Assessment scope, evidence and terms A clear boundary One legal entity, one business unit and one workflow. Up to three recordings, a leadership interview and an executive readout.
A reviewed decision pack Current-state map, three priorities, baseline, 90-day plan and one starter asset: an SOP, control checklist, requirements brief or automation blueprint.
A useful follow-through Check-ins at 30 and 90 days. Implementation and ongoing software subscriptions are separate purchases.
MAKE THE ASSUMPTIONS VISIBLE
What is today’s repeated entry costing? Start with what the work costs now. Any reduction is your assumption.
ANNUAL COST OF THIS WORK TODAY At default inputs $42,900 15 team hours / week on this workAdd an assumed time reduction to see what it would be worth. It stays an assumption, not a result.
Illustrative planning model using your inputs, not measured customer performance. Hours are per person per week. Any time reduction is your assumption and starts at zero; its value is capacity at the entered rate, not a cash saving. Excludes implementation, adoption and ongoing costs.
See the calculation Annual work cost = hours per person per week × people × loaded hourly cost × 52 weeks. Assumed capacity value = annual work cost × your assumed time reduction. This is not a promise of returns; the assessment fee and any implementation costs are not deducted.
Bring the workflow behind the system change. Use 15 minutes to define the assessment. × Redfern Industrial Supply · FICTIONAL EXAMPLE
See which exceptions the new system must handle. The authored cases can have more than one exception. Timing ends when a draft credit is ready for approval; it does not measure credit issuance, refunds or labor savings.
Cohort 50 closed return cases
Receipt-to-draft-ready duration 400 business hours across 50 returns; mean 8 hours
Item or unit code mismatch 12 of 50 returns
Missing disposition 7 of 50 returns
Unlinked credit approval 9 of 50 returns What this changes in the model ProcessIdentify → decide → link → review Data flowsSource item + unit + approved mapping StandardsTraceable evidence before draft acceptance Illustrative records. Proposed changes require validation, an accountable owner and approval before implementation.
× Redfern Industrial Supply · FICTIONAL EXAMPLE
Inspect a mapping before it becomes a requirement. The proposed workbook records unresolved mappings and their owners. A reviewed requirements specification can describe the change; implementation still needs target-system tests and approval.
Return RED-012 · legacy item AX-6 · unit CASE
Conversion question Confirm units per case before accepting target quantity
Required decisions Receipt, disposition and separate credit authority
Validation Reconcile item, unit, quantity and approved amount What this changes in the model Business rulesSeparate disposition from credit authority SystemsTestable return-to-credit mapping Data flowsSource item + unit + approved mapping OrganizationData owner, returns lead, controller StandardsTraceable evidence before draft acceptance Illustrative records. Proposed changes require validation, an accountable owner and approval before implementation.
× Redfern Industrial Supply · FICTIONAL EXAMPLE
Keep the approval when the screen changes. This authored walkthrough shows a requirement hidden between tools. Validate the actual records, permissions and supported target fields before estimating or building the migration.
Start A returned case is received under a legacy item code
Handoff Returns clerk emails the disposition to finance
Gap Draft credit does not link the approval message
Proposed check Carry return reference and authority into the draft review What this changes in the model ProcessIdentify → decide → link → review Business rulesSeparate disposition from credit authority SystemsTestable return-to-credit mapping OrganizationData owner, returns lead, controller Illustrative records. Proposed changes require validation, an accountable owner and approval before implementation.
× Redfern Industrial Supply · FICTIONAL EXAMPLE
Process The example maps the operating decisions before mapping system fields. A return must have a confirmed receipt and disposition before finance prepares the draft credit.
AS-IS Authorize → receive → search → rekey E01 · return-to-credit events
PROPOSED TO-BE Identify → decide → link → review Validate with the workflow owner before changing the live process.
Follow the evidence Authored returns and draft-credit event registerSee which exceptions the new system must handle. Authored returns-clerk and finance walkthroughKeep the approval when the screen changes. Illustrative records. Proposed changes require validation, an accountable owner and approval before implementation.
× Redfern Industrial Supply · FICTIONAL EXAMPLE
Business rules An item can be received without being approved for credit. The requirements brief must retain the authorized disposition and the separate finance approval rather than treating a status field as both.
AS-IS Disposition and credit rules live in email E02 · return-field workbook
PROPOSED TO-BE Separate disposition from credit authority Validate with the workflow owner before changing the live process.
Follow the evidence Authored return-field and decision workbookInspect a mapping before it becomes a requirement. Authored returns-clerk and finance walkthroughKeep the approval when the screen changes. Illustrative records. Proposed changes require validation, an accountable owner and approval before implementation.
× Redfern Industrial Supply · FICTIONAL EXAMPLE
Systems The proposed mapping names the source record, target field, reconciliation and reviewer. It is a requirements design; it does not establish that a particular ERP interface is supported.
AS-IS Legacy returns screen, email, ERP E03 · returns-to-finance walkthrough
PROPOSED TO-BE Testable return-to-credit mapping Validate with the workflow owner before changing the live process.
Follow the evidence Authored return-field and decision workbookInspect a mapping before it becomes a requirement. Authored returns-clerk and finance walkthroughKeep the approval when the screen changes. Illustrative records. Proposed changes require validation, an accountable owner and approval before implementation.
× Redfern Industrial Supply · FICTIONAL EXAMPLE
Data flows Twelve of fifty returns have inconsistent item or unit-of-measure codes. A mapping table needs explicit conversion and reconciliation checks so a case cannot silently become an each.
AS-IS Old item and unit codes conflict E01 · code exceptions
PROPOSED TO-BE Source item + unit + approved mapping Validate with the workflow owner before changing the live process.
Follow the evidence Authored returns and draft-credit event registerSee which exceptions the new system must handle. Authored return-field and decision workbookInspect a mapping before it becomes a requirement. Illustrative records. Proposed changes require validation, an accountable owner and approval before implementation.
× Redfern Industrial Supply · FICTIONAL EXAMPLE
Organization Separate who validates a code, who decides what happens to returned stock and who approves a credit. The implementation team needs named decision owners for each exception.
AS-IS Unclear ownership of mapping exceptions E03 · approval handoff
PROPOSED TO-BE Data owner, returns lead, controller Validate with the workflow owner before changing the live process.
Follow the evidence Authored return-field and decision workbookInspect a mapping before it becomes a requirement. Authored returns-clerk and finance walkthroughKeep the approval when the screen changes. Illustrative records. Proposed changes require validation, an accountable owner and approval before implementation.
× Redfern Industrial Supply · FICTIONAL EXAMPLE
Standards Nine returns have an email approval without a link on the credit record. Retain approval lineage when moving the workflow so the target screen does not erase the control.
AS-IS Approval is absent from the credit record E01 · approval-link audit
PROPOSED TO-BE Traceable evidence before draft acceptance Validate with the workflow owner before changing the live process.
Follow the evidence Authored returns and draft-credit event registerSee which exceptions the new system must handle. Authored return-field and decision workbookInspect a mapping before it becomes a requirement. Illustrative records. Proposed changes require validation, an accountable owner and approval before implementation.
× Redfern Industrial Supply · FICTIONAL EXAMPLE
From evidence to a practical decision. 01 Resolve item and unit mappings before migration. Create a reviewed mapping register with a data owner, explicit conversions and reconciliation examples.
Owner: Data owner · Measure: Unresolved mappings and material quantity differences in a representative test set. 02 Keep disposition as a real decision. Define disposition readiness, authority and exception handling before a return can enter draft-credit preparation.
Owner: Returns lead · Measure: Drafts prepared without an authorized disposition and the effort to resolve the gap. 03 Carry credit authority into the target record. Specify approval references and a human review gate, then test the proposed draft mapping against source records.
Owner: Finance controller · Measure: Draft credits without linked authority, mismatched amounts and receipt-to-draft-ready time. Read the full sample Illustrative records. Proposed changes require validation, an accountable owner and approval before implementation.
Preview · excluded from experiment reporting
Your privacy choices
Allow optional analytics to help us improve ProcessScout? Privacy notice
Accept analytics Reject analytics
Chat with us 

 ProcessScout Recorder Capture with permission
 EVIDENCE